

The penny challenge is a year-long savings plan where you deposit $0.01 on day one, $0.02 on day two, and add one cent every day after that. Stick with it for all 365 days and you’ll save exactly $667.95. In a leap year, that climbs to roughly $671.61. No app subscription, no big upfront commitment — just a jar, a tracker, and a penny.
Not everyone wants to handle physical coins every single day. That’s why the most popular versions of this challenge let you group deposits by week or month instead of daily. The math stays the same; the friction drops considerably.
- Classic daily version: Add one cent more each day for 365 days. Total savings reach exactly $667.95 over 365 days if you follow the classic penny challenge.
- Weekly grouping: Add up seven days’ worth of pennies and deposit once a week.
- Monthly grouping: Calculate the month’s total and transfer it in one lump sum.
- Reverse order: Start at $3.65 on day one and count down — same total, front-loaded.
You save exactly $667.95 in one year by depositing just $0.01 on day one and adding one cent each day for 365 days.
Table of Contents
- What the penny challenge actually is and why people love it
- How the classic penny challenge math works
- Popular penny challenge variations and when to pick each
- How to start your penny challenge today
- Printable templates and trackers that make it easier
- Where to store your pennies and how to cash them in
- Why the penny challenge actually builds a saving habit
- Tips to help you actually finish the challenge
- Key Takeaways
- Why I think the penny challenge is underrated as a starting point
- Ready-made penny challenge bundles from Mariaandherjournal
- Useful sources
What the penny challenge actually is and why people love it
The penny savings challenge is one of the most beginner-friendly savings methods around, and that’s not an accident. The concept is simple: you start with a single cent and increase your deposit by one cent each day. By the end of the year, your largest single deposit is a few dollars — still less than a cup of coffee.
What makes it work as a habit isn’t the dollar amount. It’s the structure. You have a clear rule, a daily action, and visible progress. That combination is what separates people who actually save from people who intend to.
Who tends to get the most out of it:
- Beginners who’ve tried budgeting apps and quit because the numbers felt abstract.
- Parents teaching kids that small, consistent actions compound over time.
- Cash users who already handle physical money and can drop coins into a jar naturally.
- Low-income savers who can’t commit to $50 or $100 a month but can always find a penny.
The challenge also has a gamified quality. Crossing off a box on a printed tracker or watching a jar fill up gives you a small win every single day. That feeling is what keeps people going past February.
How the classic penny challenge math works
The math behind the $667.95 total comes from a simple triangular number formula. When you add consecutive integers from 1 to 365 (each representing cents), the sum is 66,795 cents, which equals $667.95. Here’s how the first ten days look:
| Day | Deposit | Running Total |
|---|---|---|
| 1 | $0.01 | $0.01 |
| 2 | $0.02 | — |
| 7 | $0.07 | — |
The deposits stay tiny for months. By day 100, your single deposit is just $1.00 and your running total is $50.50. The back half of the year is where the amounts pick up — day 300 means a $3.00 deposit — but by then the habit is already locked in.
For monthly grouping, here’s roughly what each month costs (based on a January 1 start):
- January: $4.96
- February: $11.78
- March: $22.94
- April: $34.65
- May: $48.67
- June: $63.45
- July: $79.46
- August: $96.07
- September: $113.55
- October: $131.96
- November: $151.05
- December: $169.41
The monthly totals grow steadily, which is worth knowing before you start. If December’s $169 feels steep, the reverse challenge, explained next, solves that problem.
Popular penny challenge variations and when to pick each
The classic daily version isn’t the only way to run this. Several variations have emerged for different budgets, schedules, and savings goals.
-
Reverse penny challenge: Start at $3.65 on day one and decrease by one cent each day. The year-end total is identical at $667.95, but you front-load the larger deposits. This works well for people who expect their cash flow to tighten later in the year — think holiday spending, tax season, or irregular income.
-
52-week penny variant: Instead of daily deposits, you save by week. Week 1 is $0.07 (days 1–7 combined), Week 52 is $3.64. You make 52 deposits instead of 365, which is far easier to manage for anyone without daily cash on hand.
-
2,000-pennies challenge: Save exactly $20.00 per week for 50 weeks. The target is $1,000 rather than $667.95. Good for anyone who wants a rounder goal and doesn’t mind a slightly higher weekly commitment.
-
Monthly grouping: Calculate each month’s total and transfer it once. This is the recommended approach for cashless users — set a calendar reminder, calculate the month’s sum, and move it from checking to savings in one transfer.
-
Envelope system: Label 12 envelopes with each month’s target amount. Stuff cash into the envelope at the start of the month, then deposit it at the end. This works especially well if you’re already using a cash-stuffing system for your budget.
-
Scaled-up version: Multiply every daily amount by a factor. Double the deposits and you’ll save $1,335.90 in a year. Cut them in half and you save about $334. Scaling lets you hit a specific goal rather than accepting the default $667.95. For a first $1,000 savings goal, a 1.5x multiplier gets you there.
How to start your penny challenge today
You don’t need to wait for January 1. The challenge works starting any day of the year — just adjust your end date 365 days out.
- Choose your version. Pick daily, weekly, monthly, or reverse. If you’re new to saving challenges, monthly grouping is the lowest-friction entry point.
- Set a start date and end date. Write both on your tracker. Seeing a finish line matters more than most people expect.
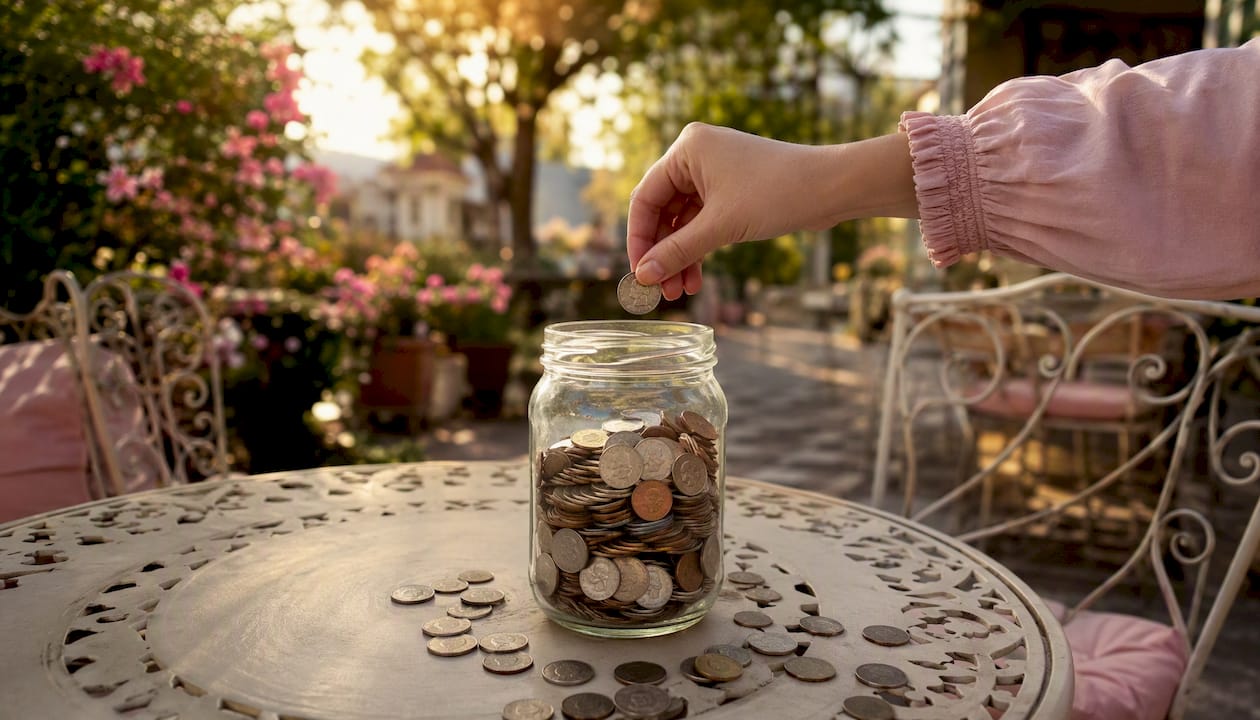
- Pick a storage method. A clear glass jar for physical coins, a labeled envelope system, or a dedicated savings account that you don’t touch for other expenses. A savings account earns interest; a jar gives you the visual satisfaction of watching it fill.
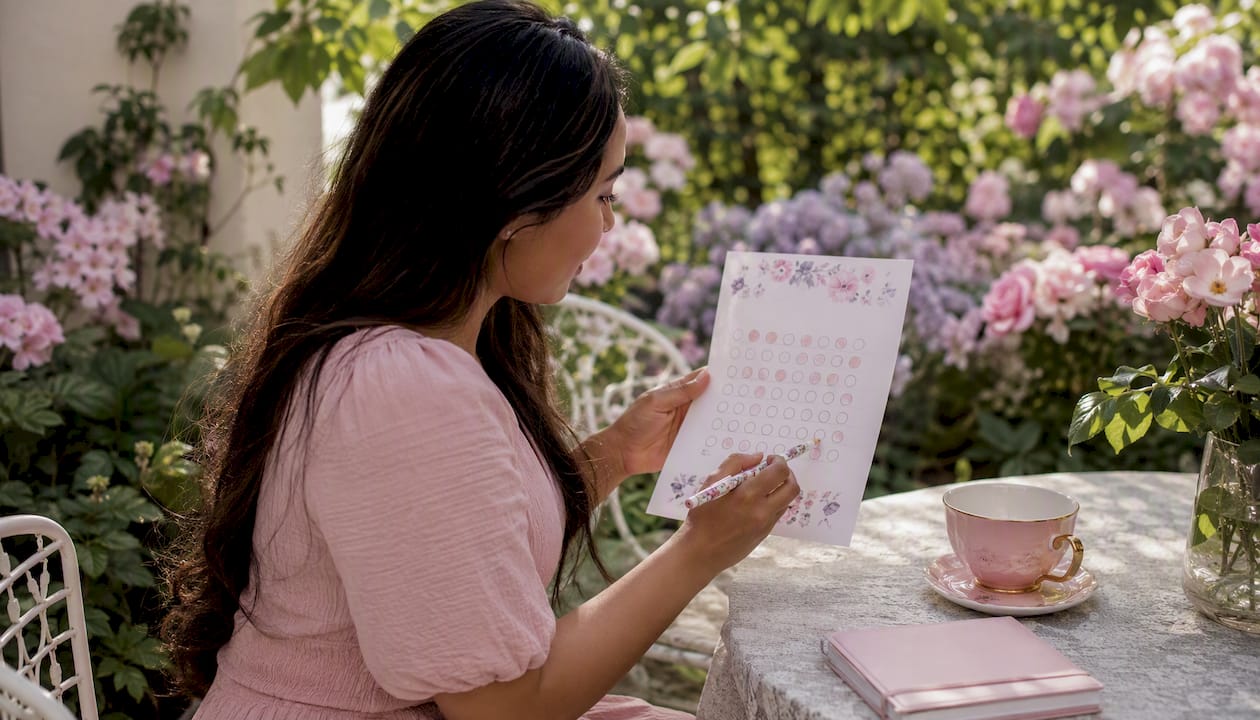
- Get a tracker. A printed 365-box calendar, a 52-week chart, or a monthly deposit log. Cross off each deposit as you make it. Printable trackers are the simplest option — print once, use all year.
- Name your goal. Write it on the jar or at the top of your chart. “Emergency fund,” “Christmas gifts,” “weekend trip” — a specific destination keeps you going when motivation dips. The penny challenge is a practical way to seed an emergency fund, pay down a small debt, or cover a short-term goal.
- Set a reminder. A phone alarm for daily depositors, a weekly calendar event for weekly groupers, or a monthly recurring transfer for the cashless version.
- Decide your catch-up rule. Miss a day? Add it to tomorrow’s deposit. Miss a week? Do a single catch-up transfer at the end of the month. The rule matters less than having one — without it, one missed day becomes two, then five.
Pro Tip: If you’re doing the monthly version, set up an automatic transfer from your checking account to a separate savings account on the first of each month. You’ll never forget a deposit, and the money moves before you can spend it.
Printable templates and trackers that make it easier
A tracker turns an abstract plan into a physical record of progress. The format you choose depends on how you’re running the challenge.
- 365-box daily calendar: One box per day, numbered 1–365. Check off each deposit as you make it. Best for daily depositors who want to see the full year at a glance.
- 52-week chart: One row per week with the weekly deposit amount and a checkbox. Cleaner and less overwhelming than 365 individual boxes.
- Monthly summary table: Twelve rows, one per month, with the target deposit and a running total column. Ideal for monthly groupers.
- Envelope labels: Pre-printed labels with each month’s target amount. Attach to a cash envelope, fill it, deposit at month’s end.
To use any of these well: mark each deposit the moment you make it, not at the end of the week. Attach a photo of your savings goal to the front of the tracker — a vacation destination, a debt payoff number, a gift you’re saving toward. That image does more motivational work than any spreadsheet formula.
Mariaandherjournal’s savings challenge bundles include handmade printable penny challenge charts, labeled cash-stuffing envelopes, and decorative accessories designed to make the whole system feel personal rather than clinical. If you want a tracker that you’ll actually want to look at every day, a handcrafted bundle beats a generic spreadsheet. You can also customize your own tracker on Canva if you prefer a fully DIY approach.
Where to store your pennies and how to cash them in
Physical coins need a plan. A jar on your desk works fine for the first few months, but by December you’ll have a significant pile of coins that need to go somewhere useful.
Storage options:
- Clear glass jar: The classic choice. Visibility is the point — watching it fill is motivating.
- Labeled envelopes: One per month, stuffed with cash and stored in a budget binder. Works well alongside a cash-stuffing system. For students or anyone new to envelope budgeting, cash envelope categories offer a useful framework.
- Dedicated savings account: No coins, no counting. Transfer the monthly total and let it sit. Some accounts earn interest on small balances, which is a small but real bonus.
Converting coins in the U.S.:
Most people don’t realize that coin-counting machines charge fees — typically a percentage of the total — while many banks and credit unions will count and deposit coins for free if you roll them first or present them in approved coin bags. The process:
- Sort coins by denomination.
- Roll them in standard coin wrappers (available free at most banks).
- Bring rolled coins to your bank teller for a free deposit.
Check your specific bank’s coin policy before you show up with a jar of loose pennies. Some branches no longer accept unrolled coins at the teller window, and a few have eliminated coin services entirely. Credit unions tend to be more accommodating than large national banks.
Why the penny challenge actually builds a saving habit
The reason this challenge works isn’t the $667.95. It’s what happens to your behavior over 365 days of consistent small action.
Starting with one cent bypasses the “all-or-nothing” resistance that kills most savings attempts. When the first deposit costs less than a gumball, there’s no psychological barrier to beginning. And once you begin, the daily action creates a chain. Breaking that chain feels worse than maintaining it — a dynamic behavioral researchers call the Seinfeld effect, after the comedian’s habit of marking an X on a calendar for every day he wrote jokes.
Physical containers reinforce this further. A jar you can see, a chart you can mark — these create tangible evidence of progress that an app balance simply doesn’t replicate. Watching a jar fill up over months produces a stronger commitment than watching a number change on a screen.
The habit is the real product. Financial experts note that the penny challenge trains the “pay yourself first” routine — and that routine tends to outlast the challenge itself, often triggering longer-term saving behavior.
Pro Tip: Attach a picture of your savings goal to the front of your jar or tracker. A concrete visual reminder — a photo of the vacation, the debt payoff number written in marker — makes the goal specific enough to pull you back on days when motivation is low.
Tips to help you actually finish the challenge
Most people who quit do so in March or April, when the novelty wears off and the daily habit hasn’t fully set. These tactics address that specific window.
- Batch your deposits. Grouping daily amounts into one monthly transfer is the single most effective way to reduce dropout. Calculate the month’s total, set an automatic transfer, and move on.
- Tell one person. Social accountability doesn’t require a public announcement. Telling a single friend or partner that you’re doing the challenge is enough to raise the cost of quitting.
- Celebrate every $100. When your running total hits $100, $200, $300 — mark it. A small reward (a coffee, a new bookmark, a night off cooking) keeps the challenge from feeling like pure deprivation.
- Keep a catch-up rule visible. Write your missed-day policy on the tracker itself. “Miss a day? Add it to tomorrow.” Seeing the rule removes the decision-making that leads to giving up.
- Connect it to a named goal. Vague saving (“for the future”) loses to specific saving (“for the December trip”). Name the goal, write it on the jar, and revisit it when motivation dips. For more saving challenge tips that stick, the pattern is always the same: specificity beats willpower.
Key Takeaways
The penny challenge saves exactly $667.95 in 365 days by starting at $0.01 and adding one cent daily — and a printable tracker or monthly batching strategy is what separates people who finish from people who quit in April.
| Point | Details |
|---|---|
| Core math | Save $0.01 on day one, add $0.01 daily; total is $667.95 in 365 days ($671.61 in leap years). |
| Best variation for beginners | Monthly grouping reduces daily friction — calculate the month’s total and transfer it once. |
| Physical trackers outperform apps | A visible jar or printed chart builds stronger commitment than a digital balance alone. |
| Name your goal | Attaching a specific purpose (emergency fund, gift, trip) to the challenge significantly improves completion. |
| Mariaandherjournal bundles | Handmade savings challenge bundles with printable charts and cash-stuffing envelopes make tracking easier and more enjoyable. |
Why I think the penny challenge is underrated as a starting point
Most personal finance advice skips straight to budgeting apps, high-yield savings accounts, and automated investing. That’s fine advice for someone who already has a saving habit. For someone who doesn’t, it’s like recommending a marathon training plan to a person who hasn’t jogged in years.
The penny challenge works precisely because it asks almost nothing of you on day one. One cent. That’s it. And in asking almost nothing, it removes the single biggest obstacle to saving: starting.
What I find genuinely interesting about the challenge is that the money itself is almost beside the point. $667.95 won’t change anyone’s financial life on its own. But the habit of setting money aside every single day — or every single month — absolutely can. The challenge is a training ground, not a destination. People who complete it tend to keep saving after it ends, often at higher amounts, because the behavior is already built in.
The physical element matters more than most digital-first advice acknowledges. A jar you can see, a chart you can mark with a pen, an envelope you can hold — these create a relationship with your money that an app balance doesn’t. That’s why handmade trackers and cash-stuffing envelopes aren’t just aesthetic choices. They’re functional tools for building the kind of tangible, visible progress that keeps people going.
Start small. Pick a goal that actually means something to you. And use a tracker you’ll want to look at every day.
Ready-made penny challenge bundles from Mariaandherjournal
Skipping the setup is the fastest way to actually start. Mariaandherjournal’s handmade savings challenge bundles include a printable penny challenge chart, labeled cash-stuffing envelopes sized for monthly deposits, and a decorative beaded paperclip bookmark to mark your place in a budget binder or planner. Everything arrives ready to use — no designing, no printing decisions, no sourcing envelopes separately.
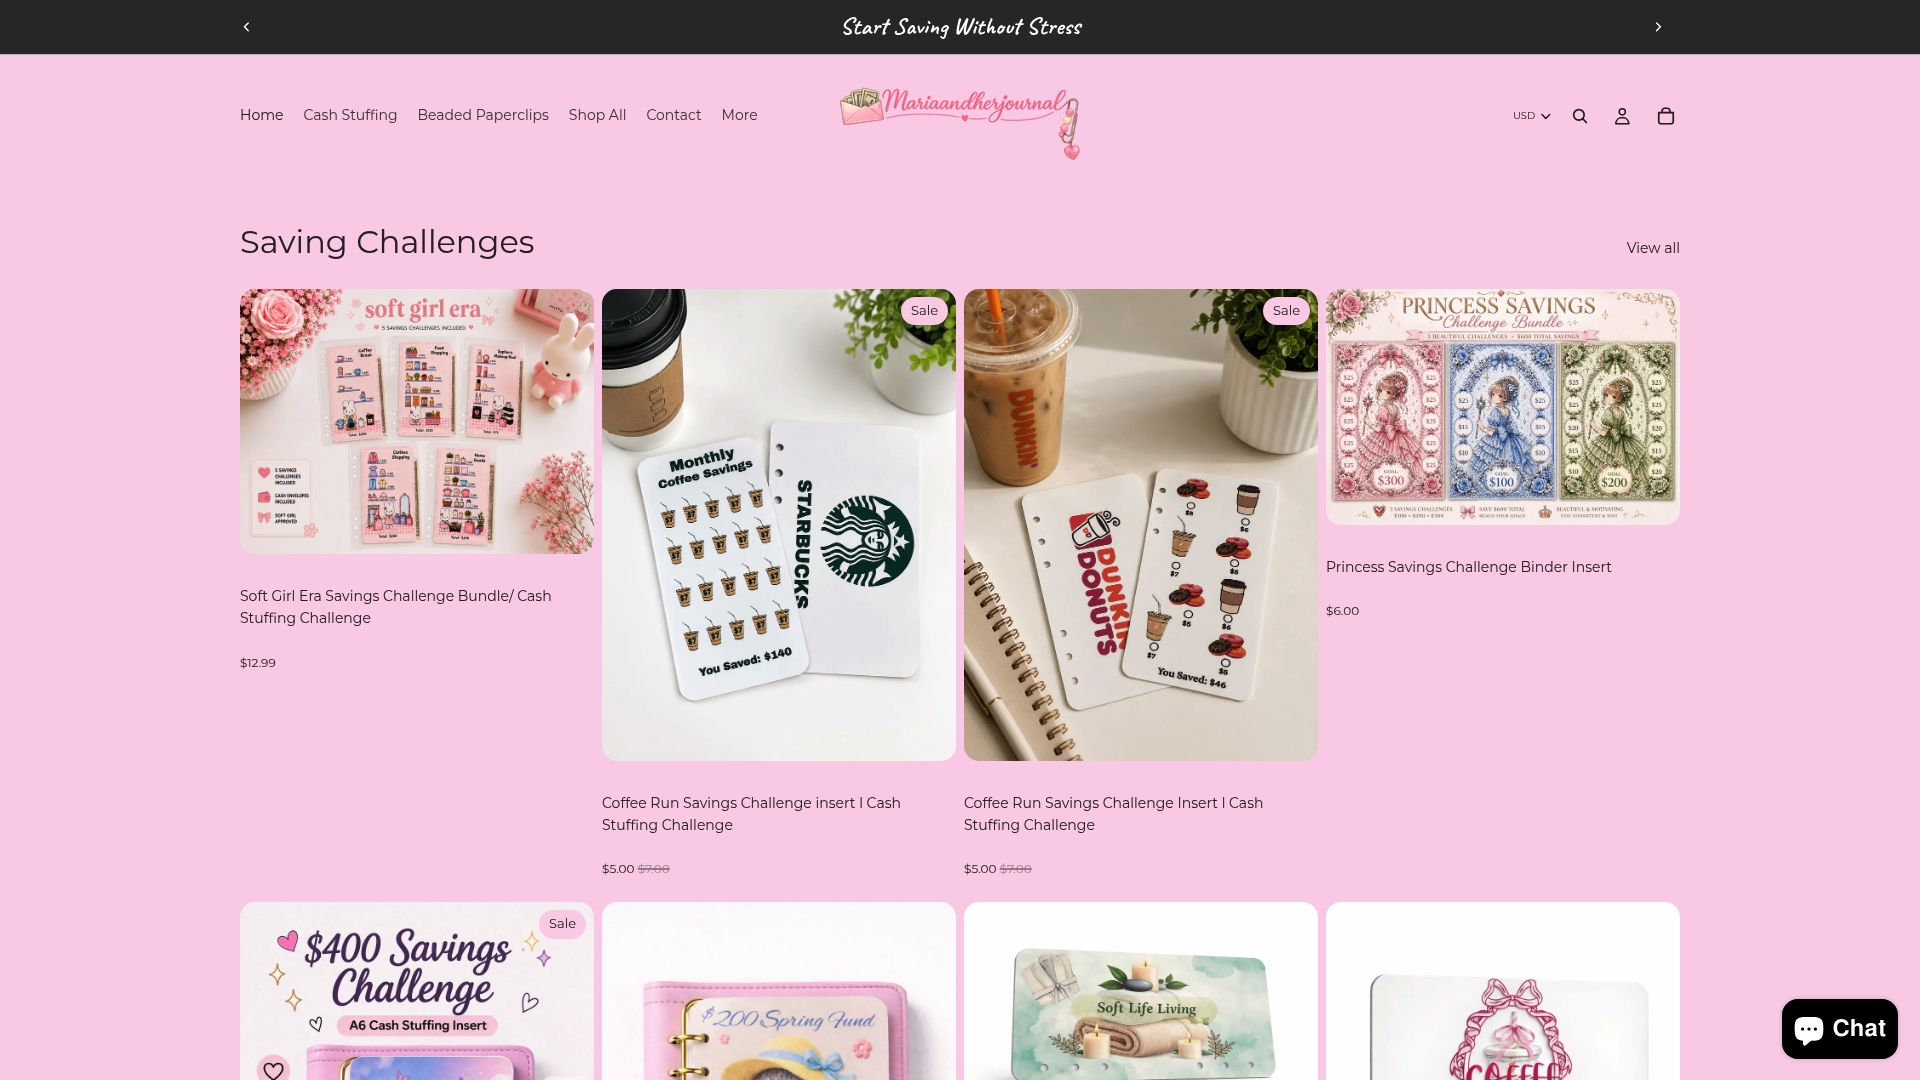
The bundle cuts setup time to minutes and gives you a physical system that’s genuinely pleasant to use. A tracker you like looking at is a tracker you’ll actually fill in. Browse the savings challenge collection and pick the bundle that fits your goal — then start today, not January 1.
Useful sources
- How to save $668 in a year with the penny-a-day savings challenge — Yahoo Finance
- How the Penny Challenge Can Supercharge Your Savings — Wallet Hacks
- The Penny Challenge: A Step-by-Step Guide To Saving Over $600 — Yahoo Finance
- The Penny Challenge Can Help You Save More Than $600 — The Penny Hoarder
- Money Saving Challenges — NatWest
- How to Do the 1p Savings Challenge 2026 — Mariaandherjournal
- 11 Easy Savings Challenges for Beginners — Mariaandherjournal
- Unique gifts for creative hobby lovers: 2026 guide — Lembradia