

The weather savings challenge is a temperature-linked savings method: check the forecasted high (or low) for the day or week, then transfer that dollar amount into a dedicated savings account. If Wednesday’s high is 67°F, you save $67. That’s the whole rule. It works best for people who want a concrete, external trigger to build a saving habit rather than relying on willpower alone.
To start today: pick daily or weekly cadence, choose your temperature source (Weather.com, your phone’s weather app, or a local TV forecast), and make your first transfer. Done.
Key Takeaways
The weather savings challenge works because it replaces willpower with an external trigger: the daily forecast tells you exactly how much to save, removing the hardest part of building a money habit.
| Point | Details |
|---|---|
| Core rule | Check the forecasted temperature and save that dollar amount daily or weekly. |
| Best adaptations | Use the daily low, last-digit rule, or a monthly cap in hot climates or on tight budgets. |
| Habit over dollars | Consistency matters more than the total; tying saving to a daily routine builds the reflex. |
| Quarterly review | Check every three months that the challenge hasn’t displaced essential savings or sinking funds. |
| Mariaandherjournal | Handmade printable bundles and cash-stuffing envelopes give tactile savers a ready-made tracking system. |
Table of Contents
- How does the weather savings challenge actually work?
- What can you realistically save? Three worked examples
- Benefits and drawbacks worth knowing before you start
- How to make the challenge sustainable over time
- Tracking methods that actually help you stick with it
- A 7-step checklist to launch your challenge today
- How Mariaandherjournal’s printable bundles support this challenge
- Why printable tools outperform apps for habit-building challenges
- Ready-made trackers from Mariaandherjournal
- Sources
How does the weather savings challenge actually work?
The core rule is simple. Check the forecasted temperature, save that dollar amount. But the version you choose matters a lot, especially if you live somewhere with extreme highs or a tight monthly budget.
Common variants:
- Daily high: Save the day’s forecasted high in dollars ($72°F = $72). High totals, high variability.
- Daily low: Save the overnight low. Smaller, more predictable amounts. Fidelity recommends this for people in extreme climates where daily highs can spike past $100.
- Weather Wednesday: Save only on Wednesdays using that day’s high or low. Bank of America’s Better Money Habits describes this as one of the most popular weekly savings challenge formats because it limits exposure to one transfer per week.
- Weekly high: Save the week’s highest temperature once, on a set day. Predictable scheduling, one decision per week.
- Last-digit rule: Take the temperature’s last digit as your dollar amount. 74°F becomes $4. A practical low-budget option.
- Cents rule: Save in cents instead of dollars. 74°F becomes $0.74. Ideal for beginners or anyone on a very tight budget.
Pro Tip: If you live in Phoenix or Miami where summer highs routinely hit 95°F–105°F, the daily high variant can push monthly totals past $2,500. Switch to the daily low or the cents rule to keep the challenge affordable year-round.
| Variant | Predictability | Effort | Typical monthly range |
|---|---|---|---|
| Daily high | Low | Daily | an amount that can vary widely but may be high |
| Daily low | Medium | Daily | an amount typically lower than the daily high variant |
| Weather Wednesday | High | Weekly | a modest and more manageable amount weekly |
| Weekly high | High | Weekly | a moderate amount weekly |
| Last-digit | High | Daily | a small amount daily |
| Cents rule | Very high | Daily | a very small amount daily |
What can you realistically save? Three worked examples
These examples use U.S. regional temperature averages to show what each variant produces over a month and a year.
Example 1: Daily high, temperate climate (Chicago, October) Average daily high: 55°F. Saving $55 per day × 31 days = $1,705 for the month. Annualized across all seasons (averaging roughly $60/day): approximately $21,900 per year. That’s a significant commitment, which is why a cap or a lower-effort variant often makes more sense.
Example 2: Weekly high, hot climate (Dallas, summer) Weekly high averages 98°F in July. Saving $98 once per week × 4 weeks = $392 for July. Across a full year with seasonal variation (averaging roughly $72/week): approximately $3,744 per year. Far more manageable, and the weekly aggregation prevents a single 105°F day from blowing the budget.
Example 3: Last-digit rule, any climate, low budget Daily high of 68°F → save $8. Daily high of 91°F → save $1. Average last digit across a year is roughly $4–$5 per day. Monthly total: $120–$155. Annual total: $1,460–$1,825. This is the version personal finance explainers highlight for anyone who wants the habit without the financial strain.
Climate note: If you’re in a cold northern state, winter lows can drop below zero, making the daily low variant impractical for those months. Switch to the last-digit or cents rule in winter, then return to the daily high in spring. Seasonal flexibility is not cheating; it’s smart budgeting for weather changes.
Benefits and drawbacks worth knowing before you start
The weather savings challenge has a genuine behavioral edge. Yahoo Finance’s personal finance coverage makes the point clearly: tying saving to a daily routine like checking the weather creates a built-in reminder that improves consistency more than the raw dollar total. You’re not relying on motivation. The weather does the prompting.
Benefits:
- Builds a daily or weekly saving habit with an external trigger
- Gamification effect keeps it interesting longer than fixed-amount challenges
- Flexible enough to scale up or down by switching variants
- Works as a savings challenge idea for any income level when you choose the right version
Drawbacks:
- Daily high variant is highly unpredictable, making monthly budgeting harder
- A heat wave or cold snap can create deposits you can’t afford
- Novelty fades; without a tracker, most people quit within 60 days
- Hot climates make the standard dollar-per-degree rule unaffordable without modification
When to avoid it: If your budget is already stretched to cover rent, utilities, and groceries, don’t let this challenge pull from those funds. Financial planners caution about budget drift, where fun novelty challenges quietly displace essential savings. Treat the weather challenge as a discretionary savings layer, not a replacement for your emergency fund or bill payments.
This article provides general information only and is not individualized financial advice. Consult a qualified financial professional for guidance specific to your situation.
How to make the challenge sustainable over time
The biggest reason people quit savings challenges isn’t lack of motivation. It’s that the rules stop fitting their cash flow. A few structural fixes prevent that.
Adaptation options:
- Set a monthly cap ($200, $300, whatever fits) so no single hot month wrecks your budget
- Use weekly averaging: add up seven days of highs and divide by seven, then save that average once
- Switch to the daily low in summer, daily high in winter, to smooth out seasonal swings
- Allow make-up deposits for missed days rather than abandoning the challenge entirely
- Split large deposits across two paycheck dates if a single transfer feels too big
Aligning with sinking funds: The weather challenge works best as a labeled, separate goal. Seasonal sinking funds convert predictable annual expenses into small, scheduled contributions, and experts recommend labeling sub-accounts and automating transfers so the balance doesn’t get accidentally spent. Apply the same logic here: open a dedicated sub-account, label it “Weather Challenge 2026,” and route transfers there automatically.
For a deeper look at how sinking funds and emergency funds interact, Mariaandherjournal’s guide on sinking funds vs emergency funds is a practical starting point.
Quarterly review checklist:
- Is the monthly average deposit still within your discretionary budget?
- Has the challenge displaced any essential savings category?
- Do you want to switch variants for the next season?
- Is the tracker still working, or do you need a new format?
Pro Tip: Automate the transfer the morning after you check the forecast. Set a calendar reminder at 7 AM, check the weather, open your banking app, and transfer. The whole process takes under two minutes and removes the decision fatigue that kills most challenges.
Tracking methods that actually help you stick with it
A tracker isn’t optional. Without one, you lose the visual progress that makes the challenge rewarding.
- Printed tracker with pen: Write each day’s temperature and deposit in a weekly row. Seeing the numbers fill in is motivating in a way that a bank statement isn’t. A savings challenges book keeps everything in one place and prevents the tracker from getting lost.
- Cash envelopes / cash stuffing: Physical cash in labeled envelopes makes the savings tangible. Pull the exact dollar amount from your wallet and stuff the envelope. Works especially well with the last-digit or cents variant.
- Labeled bank sub-accounts: Most U.S. banks and credit unions (including those using apps like Ally, Capital One 360, or SoFi) allow you to name sub-accounts. Label one “Weather Challenge” and transfer directly.
- Saving apps with automatic rules: Some apps let you set rules based on triggers. A calendar-based recurring transfer set to your weekly average is a reasonable substitute if daily manual transfers feel like too much friction.
Mix methods if you want: use cash stuffing for the tactile habit, then deposit the envelope into the sub-account at the end of each week.
A 7-step checklist to launch your challenge today
- Choose your variant. Daily high, daily low, Weather Wednesday, weekly high, last-digit, or cents. Match it to your climate and budget.
- Pick your temperature source. Weather.com, your phone’s native weather app, or a local TV station’s forecast. Use the same source every time for consistency.
- Set your cadence. Daily or weekly. Weekly is easier to sustain for most people.
- Decide on rounding and a cap. Round to the nearest dollar. Set a monthly cap that fits your discretionary budget.
- Select your tracking method. Printed tracker, cash envelopes, bank sub-account, or app. Pick one and commit.
- Set automation or calendar reminders. A 7 AM daily reminder or a recurring weekly transfer removes the decision from your plate.
- Label the goal. Is this a sinking fund for a specific purchase, or discretionary savings? Decide before you start so the money has a destination.
Protect essential savings first. If $50/week is your emergency fund contribution, that transfer happens before the weather challenge does.
How Mariaandherjournal’s printable bundles support this challenge
Mariaandherjournal’s savings challenge bundles are handmade printable sets designed specifically for tactile savers who want a physical record of their progress.
What’s typically included:
- Weekly and monthly tracker sheets with rows for temperature, deposit amount, and running total
- Cash-stuffing envelopes labeled by goal or month
- Sticker labels and usage guides for first-time challenge runners
Customers report that having a dedicated, well-designed tracker increases both consistency and enjoyment compared to a blank spreadsheet. The physical act of writing in a number after each transfer reinforces the habit in a way that a bank notification doesn’t. Pair the printed tracker with a labeled bank sub-account and a quarterly review, and you have a complete system.
Why printable tools outperform apps for habit-building challenges
Most savings apps are built for passive tracking. They record what already happened. A printed tracker asks you to engage actively: write the temperature, calculate the deposit, fill in the row. That small act of attention is exactly what makes a habit stick in the early weeks.
The first 30 days of any savings challenge are the hardest. Treat them as an experiment, not a commitment. If the daily high variant feels too aggressive after two weeks, switch to Weather Wednesday or the last-digit rule. The goal in month one isn’t to hit a dollar target. It’s to build the reflex of checking the weather and moving money. Once that reflex is automatic, scaling up is easy.
Mariaandherjournal’s beginner guides walk through how savings challenges work for anyone who wants a broader foundation before starting.
Ready-made trackers from Mariaandherjournal
If building your own tracker from scratch sounds like one more thing to figure out, Mariaandherjournal’s cash stuffing and savings challenge bundles give you a ready-to-use system. The bundles are handmade, designed for visual savers, and include everything needed to run the weather challenge from day one: tracker sheets, envelopes, and labels.
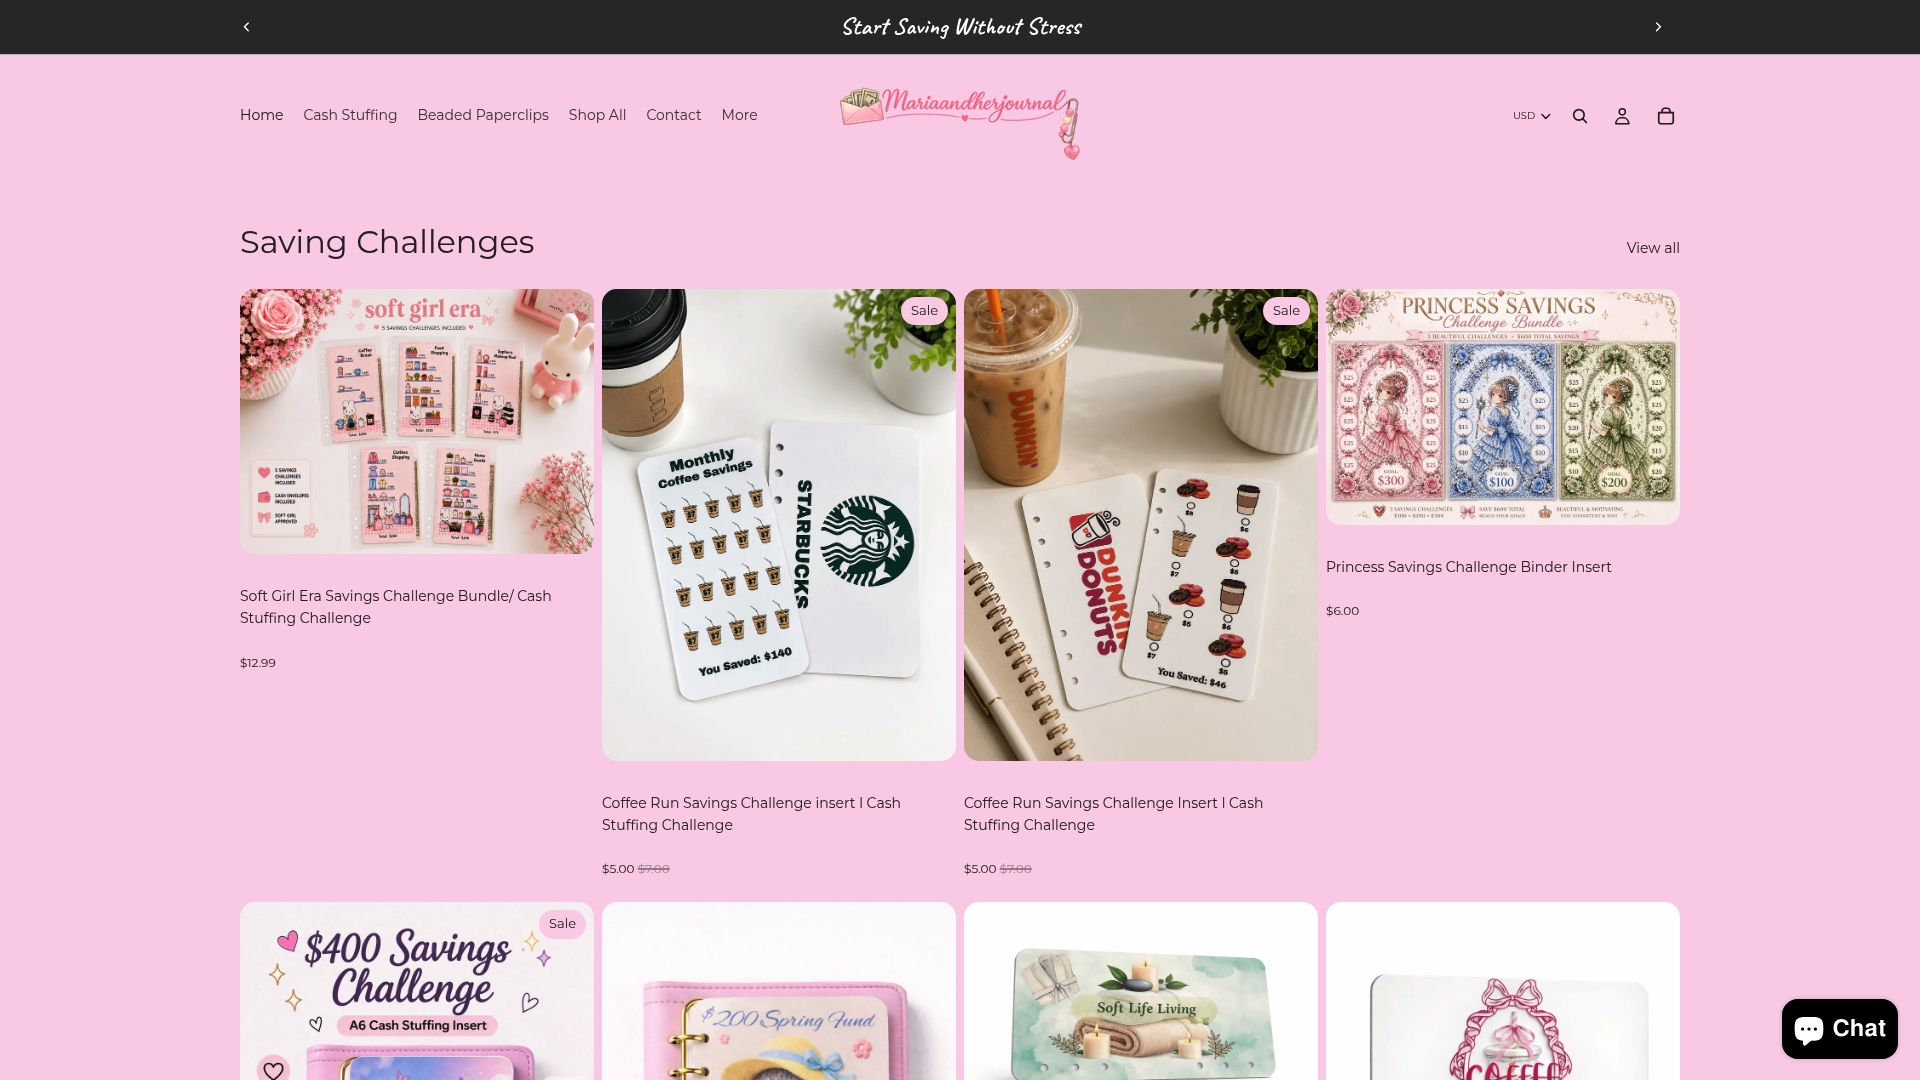
They’re a good fit for beginners who want structure without setup time, and for planner lovers who find that a beautiful tracker makes them far more likely to actually use it. Customers report that the designed layout increases how consistently they track compared to a blank notebook page. The bundles are optional; the challenge works without them. But if a well-made physical tool is what gets you past week two, it’s worth it.
Browse the saving challenges collection to find the bundle that fits your cadence and style.
Sources
These resources informed this article and offer deeper guidance on savings challenges, sinking funds, and seasonal budgeting. They are general resources and not individualized financial advice.
- 10 money savings challenges for 2026 | Fidelity
- The weather savings challenge explained: How to turn the daily forecast into meaningful savings
- How to plan for seasonal expenses
- Seasonal sinking funds: plan for annual expenses without stress | FinHelp
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.